
Australian mortgage holders have been hit with another increase in borrowing costs after the Reserve Bank lifted the cash rate by 25 basis points to 4.60 per cent, its fourth increase this year and the highest level since 2011.
The Reserve Bank’s Monetary Policy Board voted unanimously on Tuesday to raise the rate from 4.35 per cent, warning that inflation remained too high and that risks identified earlier in the year were now materialising.
For households already being squeezed by mortgages, groceries, insurance, electricity and sharply higher fuel prices, the latest move potentially means another increase in monthly repayments — and the RBA has made clear that further rate rises remain possible.
The cash rate has now climbed a full percentage point during 2026, following 25-basis-point increases in February, March, May and September.
The financial impact is increasingly difficult to ignore.
Finder data for September shows the average variable owner-occupier mortgage rate was about 6.90 per cent before Tuesday’s decision. If a lender passes the RBA increase through in full, that illustrative rate would rise to about 7.15 per cent.
For borrowers with large mortgages, that takes monthly repayments into territory that would have been almost unthinkable during the ultra-low interest-rate years.
What the latest rate rise could mean for your mortgage
The following estimates assume a 30-year principal-and-interest loan, no offset balance, a rate rising from 6.90 per cent to 7.15 per cent, and the full 25-basis-point increase being passed on by the lender.
| Outstanding loan | Before hike at 6.90% | After hike at 7.15% | Extra each month | Extra each year |
|---|---|---|---|---|
| $500,000 | $3,293 | $3,377 | $84 | $1,008 |
| $750,000 | $4,940 | $5,066 | $126 | $1,513 |
| $1,000,000 | $6,586 | $6,754 | $168 | $2,017 |
The figures are illustrative. Actual repayments depend on each borrower’s interest rate, remaining loan term, repayment structure, offset balance and whether their lender passes the increase through in full.
That means a household carrying a $1 million mortgage could be paying around $6,754 every month, or more than $81,000 a year, simply to service principal and interest under the assumptions above.
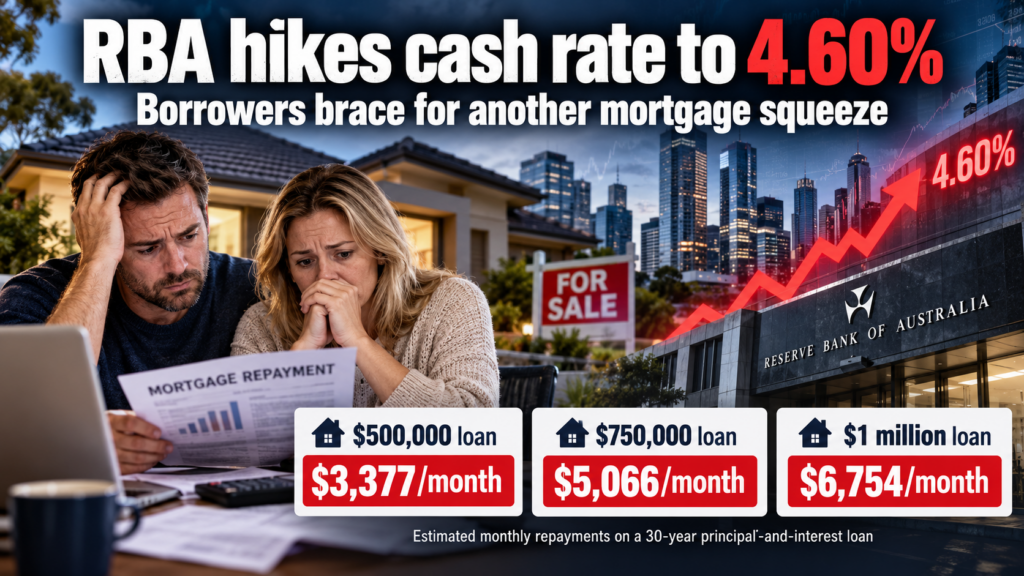
A borrower with $750,000 outstanding would be looking at approximately $5,066 a month, while a $500,000 mortgage would require about $3,377 a month.
Independent estimates using different loan-rate assumptions show a similar direction of travel. Canstar calculations reported by ABC before the decision estimated that a 25-basis-point rise would add about $114 a month to a $750,000 mortgage and $152 a month to a $1 million mortgage.
The variation between estimates reflects differences in assumed mortgage rates and remaining loan terms, but the message for borrowers is the same: another rate rise means another permanent claim on household income unless rates subsequently fall or borrowers refinance.
The September increase is particularly painful because it follows three rate rises earlier this year.
Canstar estimated that after four 25-basis-point increases during 2026, a borrower with a $750,000 mortgage could be paying about $454 more every month than before the tightening cycle began this year. For a $1 million mortgage, the increase was estimated at around $606 a month.
That works out to roughly $5,448 a year in additional repayments on a $750,000 loan and $7,272 a year on a $1 million loan, compared with the beginning of the year under Canstar’s assumptions.
And borrowers have been warned that the September increase may not necessarily be the last.
The RBA said it would continue doing what it considered necessary to return inflation sustainably to its target range and explicitly said that could include raising the cash rate further if required.
The Board pointed to a combination of international and domestic pressures.
The conflict in the Middle East has broadened, disrupting global oil supply and pushing energy prices higher than the RBA had previously assumed.
Those higher fuel costs are now flowing through into prices elsewhere in the economy, as transport and production costs increase.
The RBA also singled out another increasingly important source of global inflation: artificial intelligence.
Rapid investment in AI infrastructure is driving demand for technology-related goods and equipment globally, pushing up prices in those sectors.
At home, businesses continue to report cost pressures, with some already increasing prices and others preparing to do so.
The RBA said recent Australian inflation readings had also been stronger than expected when the Board last met.
The most recent Australian Bureau of Statistics inflation data available before Tuesday’s decision showed headline inflation running at 3.5 per cent in the year to July, while trimmed-mean inflation — a measure watched closely by the RBA — remained at 3.6 per cent. Both were above the Reserve Bank’s 2–3 per cent target band.
The next monthly CPI report, covering August, is due to be released on Wednesday — just one day after the rate decision.
The rate rise comes even as parts of the economy are visibly slowing.
The Reserve Bank acknowledged that growth in consumer spending was easing, housing prices had fallen across most capital cities and new housing loans had declined noticeably.
Labour-market conditions had also eased.
But the Board said economic growth in the June quarter was somewhat stronger than expected and domestic capacity pressures remained sufficient to keep inflation risks elevated.
The central bank’s position is effectively that households may need to endure weaker spending and tighter financial conditions for longer to prevent inflation becoming entrenched.
“Growth in aggregate demand needs to remain subdued for a period,” the Board said, arguing that this was necessary to reduce pressure on the economy and bring inflation back towards target.
The immediate problem for mortgage holders is that monetary policy works precisely by putting pressure on household budgets.
Higher repayments leave families with less money for restaurants, clothing, holidays, renovations and other discretionary spending, slowing demand across the wider economy.
For heavily indebted households, however, that economic mechanism is experienced much more directly: hundreds of dollars disappearing from disposable income every month.
And Australia’s mortgages are getting larger.
Canstar analysis using ABS lending figures put the average new owner-occupier mortgage at approximately $731,000 in the June quarter of 2026, up from around $678,000 a year earlier.
That means a relatively modest-looking 0.25 percentage-point rate increase can translate into a substantial dollar increase for households.
The political reaction was immediate.
Treasurer Jim Chalmers acknowledged the added pressure on mortgage holders and pointed to global inflationary forces, particularly higher oil prices stemming from conflict in the Middle East.
Opposition Leader Angus Taylor, meanwhile, described the decision as a “dark day” for Australians with mortgages and argued government spending had contributed to domestic inflation pressures.
Those competing explanations will form part of the political argument, but the Reserve Bank itself has identified both global shocks and domestic capacity pressures as contributing to the inflation problem.
For borrowers, the distinction offers little immediate relief.
Macquarie Bank became one of the first lenders to announce it would pass the latest 25-basis-point increase through to variable mortgage customers, with the higher rates taking effect in October.
Other lenders will determine their own pricing, although Australia’s major banks passed the previous May RBA increase through to variable mortgage customers in full.
The rate increase also hits prospective buyers.
Higher mortgage rates reduce the maximum amount banks will generally lend because repayments must pass serviceability tests.
Canstar estimated before Tuesday’s decision that the 2026 rate increases had already substantially reduced borrowing capacity, particularly for households reliant on one or two average full-time incomes.
That creates an increasingly uncomfortable housing equation.
Property prices may soften as higher rates suppress demand, but buyers also lose borrowing power and face higher repayments on whatever they do purchase.
Existing owners, meanwhile, must find additional money each month even as other household costs continue to rise.
The RBA says the alternative — allowing inflation to become entrenched — would ultimately inflict greater damage, particularly on households with lower incomes.
But after four rate rises in less than eight months, the inflation fight is being felt increasingly at the kitchen table.
For a household with a $500,000 mortgage, Tuesday’s decision could mean roughly another $1,000 a year under an average-rate scenario.
For a $750,000 borrower, it could mean another $1,500.
And for families carrying mortgages around $1 million, the latest move alone could take another $2,000 a year from household cash flow.
With the Reserve Bank refusing to rule out another increase, the question confronting millions of Australian borrowers is no longer simply how high rates can go.
It is how much more their household budgets can absorb.
Support our Journalism
No-nonsense journalism. No paywalls. Whether you’re in Australia, the UK, Canada, the USA, or India, you can support The Australia Today by taking a paid subscription via Patreon or donating via PayPal — and help keep honest, fearless journalism alive.
